The AI Boom Has a Billing Problem: Who Pays for AI Infrastructure?
AI monetization is the real question behind the boom. From Marvell's $115B Lumentum deal to Oracle and Meta raising debt for AI infrastructure, here's who may be left holding the bill.
Every boom has a moment when the question quietly changes. For the first stretch it is "how fast can this grow?" Then one week it becomes "who is going to pay for all of it?"
This week felt like that moment for AI.
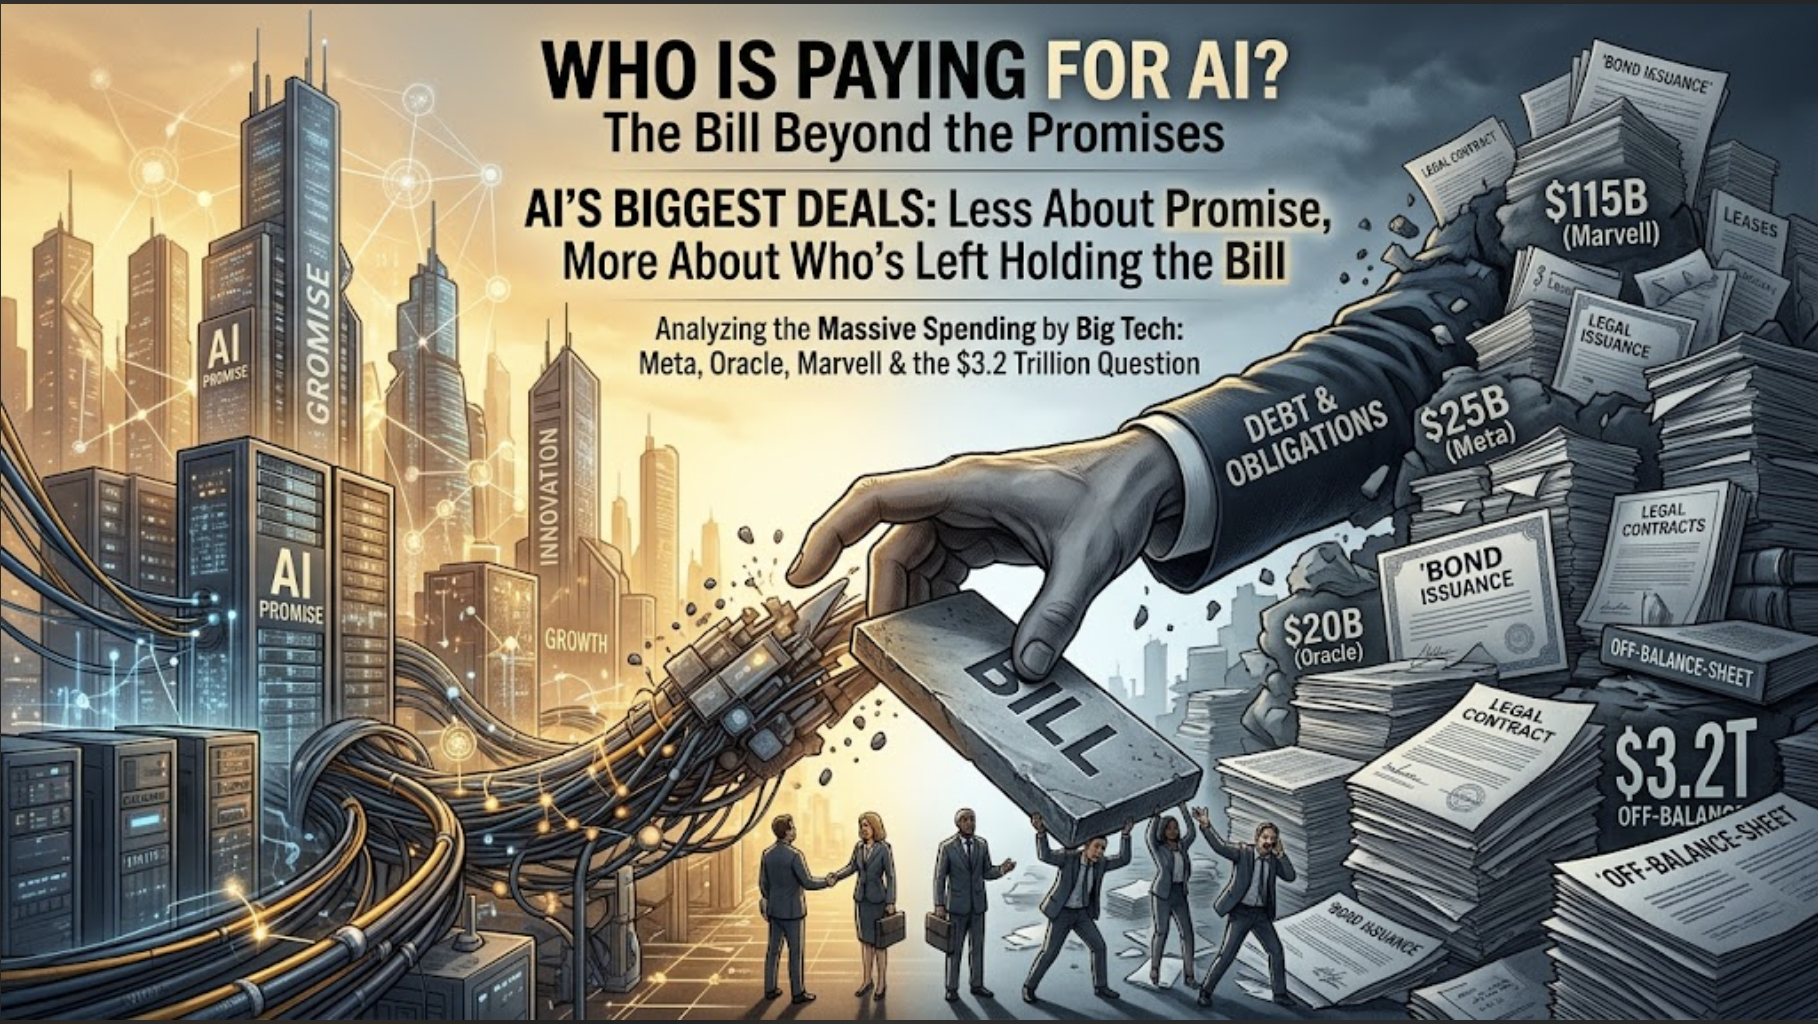
Marvell agreed to buy the optical-networking company Lumentum in a deal valued at around $115 billion. Oracle is reportedly looking for another $20 billion for its AI infrastructure. Meta is said to be weighing a bond sale of up to $25 billion. And one report put Big Tech's off-balance-sheet AI commitments near $3.2 trillion, up roughly 90%.
Read one at a time, these are four headlines. Read together, they describe a shift in how the industry is paying for its own future.
Not professional advice: This article is for general information only and is not investment or financial advice. Rules and products change and vary by country and situation. Confirm details with the official source and consult a qualified professional before making decisions.
The tell is in the funding, not the technology
For years the biggest tech companies funded their ambitions the comfortable way, straight out of profits. A company paying for experiments with cash it has already earned can be wrong without being in trouble. It shrugs, writes it off, moves on.
Borrowing removes that cushion. A bond is a promise with a date on it, and it does not care whether a chatbot feature found its audience last quarter. So when Meta and Oracle reportedly head to the debt markets for tens of billions, they are not confessing weakness. They are telling us the spending has outgrown what even their enormous cash flows can carry on their own.
That is the part worth sitting with. The costs are fixed and land on a schedule. The revenue is variable and still being discovered. Any time fixed costs go chasing uncertain revenue, the result turns on timing as much as on technology.
The $3.2 trillion you can't see on the balance sheet
The bonds, at least, are visible. The number that worries me more is the one that isn't.
Off-balance-sheet commitments are obligations that never show up as ordinary debt: multi-year leases, purchase agreements, reservations of future computing capacity. They are legal, ordinary, and not a warning sign in themselves. But economically they act like borrowing. A company cannot simply stop paying for a data center it has agreed to lease for the next decade because this quarter came in soft.
A 90% jump in that figure says something specific. The industry isn't only spending hard today. It is locking in tomorrow's spending, at fixed prices, on the bet that demand shows up on time. That is a world away from "we'll expand if the customers do."
What the Marvell deal says about AI infrastructure
It is tempting to read the Lumentum deal as one company buying another. I read it as a map of where the pressure has moved.
As AI clusters balloon, the bottleneck shifts from how much computing power you can buy to how quickly you can shuttle data between all of it. Optical connections are becoming the plumbing that decides whether expensive chips stay busy or sit idle. Money flows toward whatever is scarce, and the scarcity is sliding down the stack, away from the chips themselves and toward the wiring that feeds them.
Then there is a detail I keep coming back to. Reports describe the deal as all-stock, with Lumentum holders receiving 4.5 Marvell shares each and no cash changing hands. The price is paid in shares, and those shares are prized largely because investors believe in the AI buildout. That is a loop. Optimism lifts the stock, the stock pays for the deal, the deal feeds the story, and the story props up the optimism. Loops like this are glorious on the way up. They are also precisely what makes a change in mood so expensive.
The second bill goes to the public
There is another way to ask who pays, and voters have started asking it. One roundup of this week's news noted that data centers lost ground in the midterms, and OpenAI is now promising to take some pressure off electricity grids as data-center demand keeps climbing.
Power is where AI stops being an abstraction. Grid upgrades, local electricity prices, and land use get paid for, one way or another, by people who never signed a cloud contract. If that starts to feel unfair, the cost of building rises through permits, politics, and delay, no matter what any balance sheet says.
The AI monetization gap
Strip away the deal sizes and one question remains: AI monetization. Can the companies building generative AI turn usage into enough revenue, fast enough, to cover what they are spending?
The growth story is not in doubt. AI industry growth has been staggering, enterprise adoption of AI keeps climbing, and most forecasts for the future of AI technology point up and to the right. But growth in users is not the same as growth in profit. A free chatbot with a hundred million users is a cost center until those users, or the businesses serving them, pay more than the compute costs to run them.
This is the quiet tension under every headline. The AI hardware, the data centers, the optical links Marvell is betting on, all of it is being bought now against revenue that is still being figured out. Enterprise adoption is the most likely bridge, because businesses pay predictable subscriptions, but even that revenue has to scale faster than the infrastructure bills it is meant to cover.
What to watch next
None of this means the boom is ending. The usage is real. OpenAI says ChatGPT's search volume now runs at around a fifth of Google's. But usage is not revenue, and the distance between the two is the entire question.
Three signals will tell you more than any product launch:
- The terms on the debt. If Meta's and Oracle's raises price cheaply and fill easily, lenders are still relaxed. If the terms tighten, the mood has turned.
- Whether commitments get renegotiated. The first quiet reworking of a long-term capacity deal would be an early hint that demand is lagging the plan.
- Whether revenue catches the invoices. The industry does not need AI to be useful. It needs AI to be profitable enough, soon enough, to cover promises signed years before.
The technology may well live up to the hype. The open question is whether the payments come due before it does.
Sources
Figures here come from news reports dated early November 2026 and have not been independently verified. This piece is opinion and analysis, not investment advice.
Frequently asked questions
What is an off-balance-sheet commitment?
It's a future obligation that doesn't appear as ordinary debt on a company's balance sheet, such as a long-term data-center lease, a purchase agreement, or a reserved block of computing capacity. It's legal and common, but economically it behaves a lot like borrowing: if demand drops, you still owe the payments.
Is the AI boom about to collapse?
Nothing here says that. Usage of AI tools is real and growing. The open question is whether revenue arrives fast enough to cover spending that companies are committing to years in advance. That's a question about timing and profitability, not about whether the technology works.
Why does it matter that the Marvell–Lumentum deal is all-stock?
In an all-stock deal, no cash changes hands; the buyer pays in its own shares. Those shares are valued partly on investor belief in the AI buildout, so the deal is funded by the same optimism it reinforces. That works beautifully while sentiment is rising and gets painful if it turns.
How could the AI boom affect ordinary people?
Through power. Data centers need enormous electricity, and grid upgrades, local power prices, and land use affect people who never signed a cloud contract. If that burden feels unfair, political and permitting pushback can slow and raise the cost of building, whatever the balance sheets say.
What is the AI monetization problem?
AI monetization is the challenge of turning fast-growing usage into enough revenue to cover the cost of building and running AI. Companies are spending heavily now on AI infrastructure and hardware, while the paying demand that justifies it, especially enterprise adoption, is still catching up. The gap between usage and revenue is the core risk in the boom.
Is AI infrastructure spending sustainable?
It depends on timing. AI industry growth and enterprise adoption are strong, which supports continued investment in infrastructure, hardware, and cloud computing. The risk is that much of the spending is locked in years ahead at fixed prices, so if revenue arrives slower than planned, those commitments become hard to carry. It is sustainable only if monetization keeps pace.
Related reading
Is AI Making You Dumber? What the Research Actually Says
Can relying on AI weaken your thinking? Here's what the research actually shows about AI and critical thinking, the honest caveats, and how to use AI and stay sharp.
ChatGPT vs Claude vs Gemini: Which AI Is Best for What?
An honest ChatGPT vs Claude vs Gemini comparison: what each is best at, their limitations, multilingual strengths, pricing, and how to choose the right AI for your work.
Best AI Tools for Freelancers: What Actually Saves Time
The best AI tools for freelancers that actually save time, from writing and admin to design and scheduling, with honest guidance on where AI helps and where it doesn't.
What Is n8n? The Workflow Automation Tool Explained
A clear, honest guide to n8n: what it is, how its visual workflows and AI agents work, self-hosted vs cloud pricing, and how it compares to Zapier and Make.